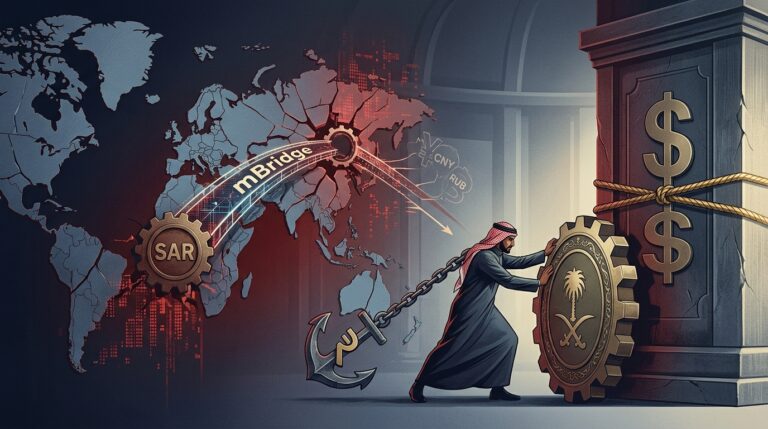
The Saudi Central Bank (SAMA) has formally concluded its participation in the China-led mBridge cross-border digital currency platform. While some market narratives frame this move as part of a broader geopolitical shift, the available evidence supports a narrower conclusion: the exit raises questions about how far Saudi Arabia is willing to go in adopting multilateral non-dollar settlement rails before official policy rationale is publicly stated.
The Mechanics of the mBridge Departure
Saudi Arabia’s withdrawal from the initiative follows the completion of its scheduled proof of concept on May 13, 2025 (Business Standard). The platform had previously been a focal point in broader energy settlement discussions between participating nations (The Standard).
To understand the policy sensitivity, the platform’s underlying structure is critical. The mBridge project operates on a distributed ledger technology (DLT) architecture designed specifically for wholesale multi-CBDC (Central Bank Digital Currency) real-time settlement. SAMA officially joined the project as a full participant in 2024, testing the viability of instantaneous cross-border clearing without relying on traditional correspondent banking networks (Bank for International Settlements).
Governance Transition and Heightened Scrutiny
The operating context for mBridge changed as the project matured. The Bank for International Settlements (BIS) Innovation Hub, which had provided a layer of multilateral institutional involvement, graduated the project and stepped back from operational oversight after the platform achieved Minimum Viable Product (MVP) status (Bank for International Settlements).
SAMA’s exit also came amid heightened scrutiny surrounding non-dollar cross-border clearing mechanisms (Business Standard). The supplied evidence does not establish that this scrutiny caused the Saudi decision. It does, however, make the governance shift relevant for assessing why central banks may prefer more controlled channels when testing alternative settlement infrastructure.
Currency Policy as an Analytical Lens
Saudi officials have not publicly stated the internal policy rationale for SAMA’s exit. That makes any motive-heavy explanation necessarily tentative.
One plausible lens is currency-policy caution. For a major energy exporter, large-scale use of non-dollar settlement channels could create questions about reserve management, liquidity, and foreign exchange exposure. But the supplied evidence does not directly prove that balance-sheet constraints drove the decision. This thesis is therefore best read as a macroeconomic hypothesis rather than an established cause.
Under that hypothesis, holding non-dollar digital balances on a multilateral ledger could be less attractive than maintaining exposure through familiar, controlled channels. The key issue is not whether non-dollar settlement is impossible, but whether an open multi-CBDC architecture offers enough practical benefit to justify the additional policy complexity for a central bank evaluating alternative settlement infrastructure.
Ring-Fencing Energy Settlement
Exiting a multilateral distributed ledger does not equate to terminating non-dollar trade with Beijing. The available reporting supports the narrower point that Saudi Arabia left mBridge after its trial phase; it does not confirm that Riyadh has abandoned future non-dollar settlement options.
A more cautious interpretation is that Saudi Arabia may prefer ring-fenced bilateral exposure over open multilateral platforms. Bilateral arrangements can allow central banks to cap exposure, manage exchange rate risks privately, and keep policy discretion concentrated within direct state-to-state channels. That remains an inference, not a confirmed Saudi policy statement.
Unresolved Questions and Next Watchpoints
The exact internal policy rationale for SAMA’s exit remains unstated by Saudi officials, leaving the weighting of regulatory caution, governance concerns, and balance-sheet considerations unconfirmed. It also remains unclear how other Gulf states will navigate their own participation in alternative settlement platforms now that the BIS has transitioned out of its oversight role.
The next concrete watchpoint for energy and currency markets is the publication of Q4 2026 bilateral trade settlement data between Riyadh and Beijing. Market observers should track whether any direct SAR-CNY settlement activity is newly disclosed, which could indicate whether experimentation is shifting away from multilateral CBDC infrastructure and toward more traditional bilateral channels.
***
*Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or legal advice. Cross-border currency platforms and foreign exchange markets carry significant risks. Readers should consult licensed professionals before making any investment or corporate treasury decisions.*
Want the full institutional-style PDF version? Enter your email for the free PDF.