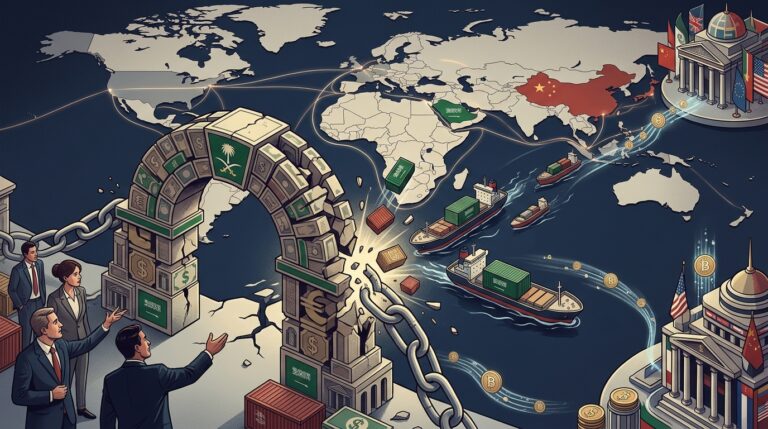
Saudi Arabia’s reported withdrawal from Project mBridge has sharpened a central question in cross-border finance: whether a faster sovereign digital payment rail can overcome the liquidity, compliance, and legal constraints that keep global trade finance anchored in existing banking networks.
The answer remains unresolved. Project mBridge shows that central banks can test shared distributed-ledger infrastructure for cross-border settlement. But Saudi Arabia’s decision to stop at the proof-of-concept stage suggests that technical interoperability is only one part of the problem. A payment system can move value quickly without replacing the reserve-currency markets, correspondent-banking relationships, and compliance architecture that make trade finance usable at scale.
What Saudi Arabia’s Exit Shows
Project mBridge was built as a shared platform for real-time, peer-to-peer cross-border payments and foreign-exchange transactions using central bank digital currencies. The Bank for International Settlements describes the project as a multi-central-bank effort that reached a Minimum Viable Product stage and used a custom distributed ledger technology design to connect participating monetary authorities: https://www.bis.org/project/mbridge
Saudi Arabia did not move from that test environment into live commercial settlement. Regional reporting said the Saudi Central Bank concluded its proof-of-concept trial on May 13, 2025, and would study broader monetary and technical policy implications before any further step: https://www.argaam.com/en/article/articledetail/id/1937915
That distinction matters. The development does not prove that multi-CBDC settlement has failed. It does show that even a major energy exporter may treat the model as experimental infrastructure rather than an immediate replacement for existing trade corridors. For commodity trade finance, the practical test is not only whether a ledger can settle a transaction, but whether exporters, banks, and central banks are willing to hold and recycle the resulting balances through liquid and legally reliable markets.
Payment Speed Is Not Reserve-Currency Depth
The hardest barrier to non-dollar settlement is not software. It is the broader financial ecosystem around the currency being used.
Trade finance depends on convertibility, offshore reinvestment options, credit lines, hedging capacity, and trusted legal finality. A distributed-ledger platform may shorten settlement time, but it cannot by itself create deep bond markets, open capital accounts, or broad commercial-bank balance-sheet demand for a restricted currency.
The National Bureau of Economic Research has examined sanctions and cross-border settlement networks, finding that substitution away from the U.S. dollar toward alternatives such as the Chinese yuan remains limited outside heavily sanctioned economies: https://www.nber.org/system/files/working_papers/w35453/w35453.pdf
That helps explain why a technically successful rail may still struggle to become a trade-finance standard. For countries with dollar-pegged currencies or large dollar-denominated reserves, accumulating non-convertible digital currency balances can create asset-liability mismatches. Settlement speed has limited value if the receiving institution cannot readily invest, hedge, or redeploy the asset through deep markets.
Sanctions Risk Still Follows the Transaction
The compliance problem is equally important. Multi-CBDC systems are sometimes discussed as possible alternatives to Western-controlled payment chokepoints, but trade banks remain exposed to secondary sanctions and access-to-market risk.
The U.S. Treasury and the Office of Foreign Assets Control have warned that foreign financial institutions can face serious consequences, including exclusion from the U.S. financial system, for facilitating prohibited transactions: https://www.gtreview.com/news/global/us-fires-secondary-sanctions-warning-to-trade-banks/
That risk does not disappear because settlement occurs on a new rail. A commercial bank using a DLT-based system still has customers, counterparties, correspondent relationships, and regulatory exposure. If a transaction involves a sanctioned party, a faster or more direct settlement mechanism does not remove the bank’s need to screen, document, and defend the activity.
This creates an asymmetric incentive. The potential efficiency gain from bypassing part of the correspondent-banking chain may be modest compared with the cost of losing access to U.S. financial markets. For many trade banks, that calculation can limit adoption even when the underlying technology functions as intended.
What Remains Unproven
Several issues remain open for Project mBridge and similar wholesale CBDC systems.
The first is participation. Saudi Arabia’s exit from the proof-of-concept track raises questions about whether other central banks will deepen involvement or limit their exposure to controlled testing.
The second is commercial liquidity. Central-bank connectivity does not automatically produce commercial-bank usage, exporter acceptance, or durable foreign-exchange market depth.
The third is legal finality. Cross-border CBDC settlement must operate across jurisdictions with different rules for insolvency, sanctions, data access, and dispute resolution. The BIS documentation supports the technical architecture and project milestones, but commercial-scale legal reliability remains a separate test.
The fourth is integration with trade finance itself. Documentary credit, supply-chain finance, and receivables finance require more than payment execution. They depend on documentation, risk assessment, collateral treatment, insurance, and bank credit appetite.
The Practical Bottom Line
Saudi Arabia’s mBridge exit is best read as a stress test for the idea that multi-CBDC rails can quickly reshape global trade finance. The project demonstrates that central banks can experiment with shared digital settlement infrastructure. It does not show that such infrastructure can independently replace the dollar-based liquidity and compliance networks that support trade flows.
For now, the central question is not whether CBDC platforms can move money across borders. It is whether they can attract enough trusted participants, usable liquidity, legal certainty, and compliance confidence to matter beyond controlled settlement environments.
***
*Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or investment advice. The analysis of geopolitical events, sanctions risks, and currency markets involves significant uncertainty. Readers should consult licensed professionals before making any financial or compliance decisions based on cross-border payment developments.*
Want the full institutional-style PDF version? Enter your email for the free PDF.