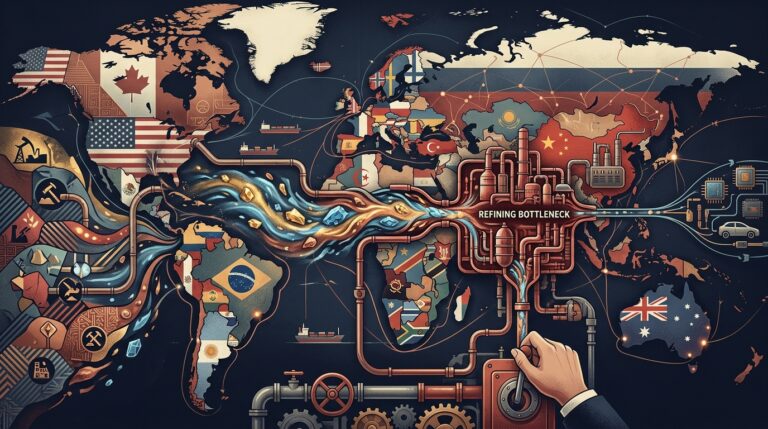
The White House has effectively sealed the border for exports of recycled critical minerals, a move aimed at onshoring strategic supply chains. However, this policy exposes a crucial gap in domestic infrastructure: the United States currently lacks the refining capacity to process the resulting glut of materials, creating a significant bottleneck that could reshape the economics of the entire recycling sector.
New DPA Export Controls on Critical Minerals
On July 30, 2026, the White House announced it was invoking the Defense Production Act (DPA) to restrict exports of recoverable critical minerals and materials source. The presidential determination specifically targets secondary feedstocks like “black mass” from shredded electric vehicle batteries and scrap from permanent magnets, which are essential for defense and high-tech applications sourcesource.
This action is part of a broader global trend. It follows China’s move in June 2026 to tighten its own export controls on strategic minerals by establishing a formal whistleblower system for violations source. These national policies reflect intensifying trade tensions and a global competition to control not just primary mining, but also the processing of these vital materials source.
The Domestic Refining Bottleneck Analysis
While the export ban successfully traps valuable scrap material within U.S. borders, it simultaneously creates an oversupply of unrefined feedstock. The core issue is that the nation’s capacity for advanced hydrometallurgical and pyrometallurgical processing—the chemical processes needed to turn black mass and magnet scrap back into battery-grade metals—is still in its infancy. Without sufficient domestic refining outlets, the raw material has nowhere to go.
This imbalance is likely to bifurcate the recycling industry. Pure-play collectors and shredders, who simply gather and prepare scrap for export, may now face a domestic market with depressed prices for their unrefined output. Their business model relied on selling to overseas processors, a channel that is now restricted. Conversely, the few domestic companies with integrated chemical refining capabilities are positioned to benefit. The export controls hand them a captive, and potentially cheaper, supply of feedstock, widening their processing margins.
What Remains Uncertain
The timeline for scaling up domestic refining capacity remains the largest unknown. While the DPA can be used to fund new projects, building specialized chemical plants is a multi-year process. It is also unclear how trading partners will react and whether they will implement retaliatory measures targeting other parts of the U.S. supply chain. The specific list of materials covered by the export controls could also be expanded with little notice, adding another layer of regulatory risk.
Next Watchpoints
For market participants tracking this space, the next key signals will come from several sources. The first is the Federal Register, which will publish the detailed implementation rules and the full list of controlled materials in the coming weeks source. The second is any forthcoming Department of Energy announcements of DPA-related funding for new domestic refining facilities. Finally, the next round of quarterly earnings calls for publicly traded recycling and specialty chemical companies will provide the first concrete data on how this policy is affecting feedstock prices and profit margins.
(Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. This article was researched and drafted with AI assistance, then reviewed by our editorial team before publication. Readers should consult with a licensed professional before making any investment decisions.)
Want the full institutional-style PDF version? Enter your email for the free PDF.